Measured. Managed. Manipulated.
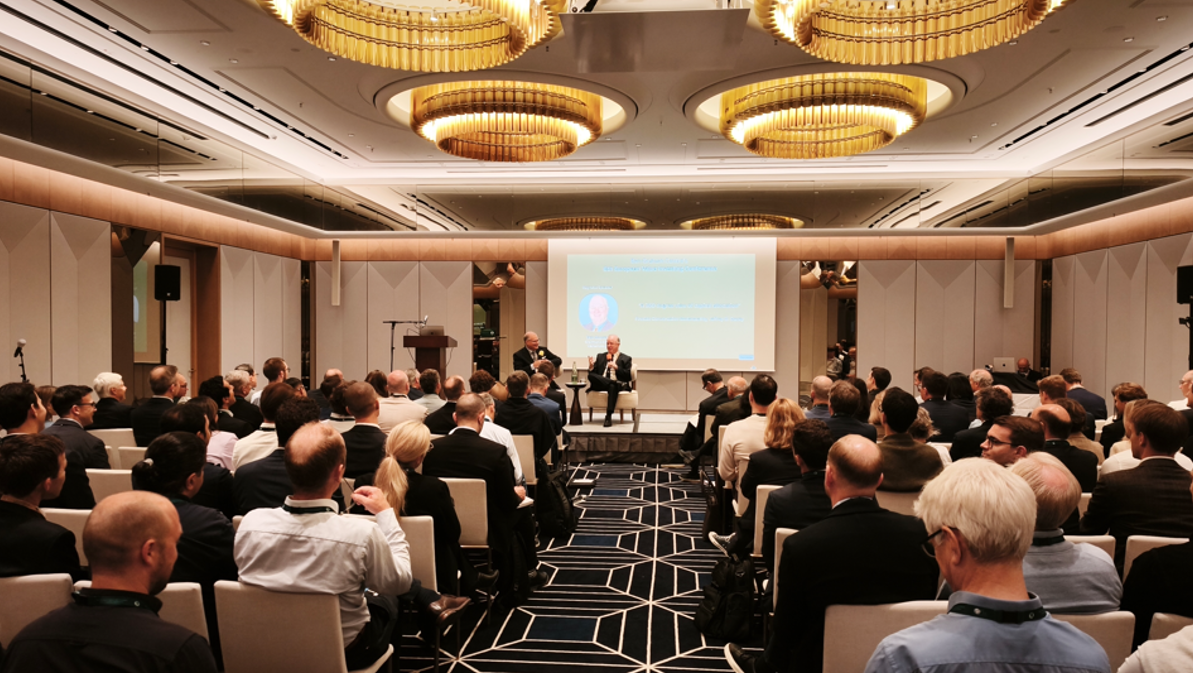
If Mr. Gayner’s chat is to be enjoyed next to a fire, Shaun’s presentation should be read as a vintage crime novel: A con man, a ringer, a twist in the final chapter. And criminally funny. Spoiler alert: I will spare you the details and tell you the ending right away. Picture this: A monkey, playing ping pong, with his hairy hand caught in a jar. Its opponent: A skinny, well-suited man using a heavy frying pan as his paddle. Defying all odds, a ping pong ball flying in between them, though I’m not sure who returned the serve.
That’s it. That’s the whole lesson. Thank you for reading.
Well… not quite.
Like every good crime novel, there is no shortage of characters: A Canadian pharma darling, a Rolls-Royce of a fund manager, a housing market that was “safe as houses”. I’m going to follow just one clue: Follow the incentives, and you’ll see where Shaun learned his trade.
A career in structured products leaves you cynical
Most people in that room know Shaun as a value investor. Fewer know that for the first 15 years of his career, he was a bond trader and portfolio manager of mortgage-backed securities, structured products and related derivatives at Goldman Sachs, Merrill Lynch and Brevan Howard.
And it shows. Not in the jargon (he kept that remarkably light, especially for a bond guy), but in the reflex: Numbers first. Downside first. Think like an underwriter, and ask the only question that really matters before you invest: How can I get hurt here?
So when a line often attributed to Peter Drucker appeared on the screen, I knew something was coming.
What gets measured gets managed.
Nobody disagrees with that. Then came Goodhart’s Law: When a measure becomes a target, it ceases to be a good measure.
And then, the version that could only come from someone who has spent his career watching people build bonds for a living:
What gets measured gets managed… gets MANIPULATED.
He brought the receipts, too. A nail factory paid by the number of nails made thousands of tiny, useless ones; paid by weight, it made a few giant, useless ones. And in the famous (possibly apocryphal) story from colonial Delhi, a bounty on dead cobras led people to breed cobras. Nobody broke the rules. Everybody did exactly what they were paid to do.
The one-number loan
Which brings us to the fixed income chapter of our crime novel.
Remember NINJA loans? No proof of Income, Job or Assets. The whole loan hinged on a single number: The credit score. One measure. And once it became the target, it was managed, and then, inevitably, manipulated.
On the other side of the table, the picture looked just as beautiful. Banks and insurers could earn a BB-like yield on a bond carrying a AAA rating, which needed a fraction of the capital. ROEs that sat around 10% could be pushed towards 30% for the most aggressive. Or, as Shaun put it: A brand-new, top-of-the-range Ferrari for the price of a used Fiat 500.
Talk about value.
Here’s where the bond trader in him really comes through. He told us the people structuring these deals found the weak spots in the rating models. Some worked out that the big institutional buyers ran the same canned scenarios, an implicit algorithm, every single time. And the least ethical in the space abused that terribly. Not by hiding the numbers, but by building bonds that were designed to pass the test rather than to survive the storm.
No mastermind was required. The whole structure was Ponzi-like, with no central character pulling the strings: Market structure and incentives simply put their thumb on the scales. And as the old joke in leveraged finance goes, a rolling loan gathers no loss. Until, of course, it stops rolling.
The truth, by the way, was there for anyone who cared to check.
In 2011, as Shaun recalls, the capital rules on CMBS mezzanine bonds changed overnight. The bonds didn’t get worse. The rules did. Same lesson, told from the other side: This time the regulator moved the measure, and the market moved with it.
Back to the ping pong table
Which, finally, explains my spoiler.
Slim’s opponents measured everything. They knew his trick with Bobby Riggs. They flew in a world champion. They had him practise for three months with the biggest frying pan they could find. They managed every variable they had measured, perfectly.
And then, as Slim told it, he walked over to the vending machine, put in two dimes, and handed the champion a Coke bottle.
He didn’t manipulate the ball. He manipulated what was being measured.
The skinny man with the frying pan is Slim: The one who beat Bobby Riggs with it, and then quietly changed the equipment. The monkey is everyone else, clutching the one thing they knew for sure, and refusing to let go even as the Coke bottle came out.
No magic formula
We think about this a lot at MAAT. There is no magic formula in investing, however much we all want one. The moment a single number becomes the reason to buy, someone on the other side of the trade is already working out how to hand it to you.
So we separate our facts from our assumptions from our opinions and try very hard never to mistake one for another. And before we invest, we ask ourselves two honest questions:
Are we analysing the data, or torturing it?
And what are the incentives of the person on the other side?
As for who returned the serve? I’m still not sure. But I know exactly who picked the paddles.
It’s true… Numbers convince. Stories seduce. And, it’s ok to let go.
-Jenny Ngan, Head of Business Development
Presenter: Shaun Heelan, Chief Investment Officer, MAAT Investment Group, Munich, Germany
Watch the speech here:
This post is for informational andeducational purposes only and does not constitute investment advice, research,or a solicitation to buy or sell any security. Companies and investmentsmentioned are discussed for illustrative purposes only and are not recommendations.Views attributed to Shaun Heelan are drawn from his remarks at the Ben GrahamCentre for Value Investing’s 6th European Value Investing Conference in Munich.Maat Investment Group GmbH is licensed by BaFin (reference 10164363) and registeredwith the U.S. SEC (CRD: 332840). Registration with the SEC does not imply acertain level of skill or training.